TL;DR

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
A 62-year-old retiree in Jefferson City, Missouri, told Kiplinger he reached $1 million about 10 years ago and now has more than $2 million. He attributes the growth to regular contributions to an IRA and a state deferred-compensation plan, invested in low-cost equity mutual funds. His account is an anonymous personal profile, not independently verified financial advice.
A 62-year-old retiree in Jefferson City, Missouri, says he accumulated more than $2 million after reaching the $1 million mark about a decade ago, according to an anonymous profile published by Kiplinger. He attributes his savings to regular contributions to an individual retirement account and a state employee deferred-compensation plan, with the money invested in low-cost equity mutual funds.
The man, who retired recently from a state government program-manager job, said his salary ranged from $60,000 to $70,000. He told Kiplinger that throughout his career he maximized his annual IRA contributions and contributions to his state deferred-compensation plan, which he described as working like a traditional IRA. He said he invested the money in low-cost equity mutual funds.
He reported an average annual return of about 9.5% over more than 30 years. That figure is his account of his investment history, not a verified performance record or a projection of future returns. The profile does not specify the exact account balances, contribution amounts, fund holdings, or how the return was calculated.
The retiree said he has kept the same investments and has not changed his lifestyle after crossing the million-dollar threshold. In recent years, he has increased charitable contributions and taken a couple of vacations. He described the main benefit as greater security and freedom, while saying he has long been content to live below his means.
A Long-Term Saving Approach
The profile offers a personal example of how a worker with a moderate public-sector salary says decades of steady saving and investing helped build substantial assets. Its central point is not a particular fund or a promise of a specific return: the retiree credited consistent contributions, time in the market, and restrained spending with helping him reach his goal.
His experience also illustrates a retirement-planning issue that can emerge after years of tax-deferred saving. He said he now anticipates higher tax bills when required minimum distributions begin and plans to make Roth conversions in the intervening years. The profile does not provide the information needed to evaluate the tax impact of that plan, which depends on individual circumstances.
Readers should treat the account as a single person’s reported experience. Kiplinger says its profiles are meant to show different paths to building savings, not to provide financial advice. The reported return and account total should not be taken as a typical result or an indication of future performance.
Products Worth Considering
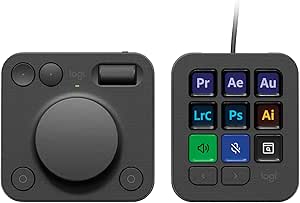
Logitech MX Creative Console with 9 Customizable Keys, Graphite

Apple MacBook Air 13.6-inch with M5 chip, 16GB Memory, 512GB SSD, Midnight

Dell 27 Plus QHD Monitor (S2725DSM), 27-inch, 144Hz, Ash White
As an affiliate, we earn on qualifying purchases.
From State Employment to Retirement
The interview is part of Kiplinger’s My First $1 Million series, which publishes accounts from people who say they have accumulated at least $1 million. The publication describes participants as anonymous to readers; in this case, the source identifies the subject as married, 62, and living in Jefferson City, but does not name him.
According to the interview, he reached $1 million around 10 years before the profile and has since grown his reported assets to more than $2 million. He said he recently retired at 62, although he could have left work earlier, and chose to continue because he enjoyed his job. The source material does not establish the precise dates of his career, contributions, retirement, or the profile’s publication.
He said his father introduced him to mutual funds and long-term investing. He did not work with a financial adviser and said he had not read books that guided his investing. Looking back, he wishes he had used Roth accounts earlier rather than traditional IRAs, though he noted Roth accounts may not have been available when he began saving. He now plans annual Roth conversions before required distributions begin, but provided no conversion schedule or tax estimates.
“In more than 30 years of investing, my annual return is about 9.5%.”
— The anonymous retiree, speaking to Kiplinger
Details the Profile Leaves Open
The account is anonymous and based on the subject’s interview. The supplied material does not say whether Kiplinger independently verified the reported $1 million milestone, current total, salary history, or investment return. It also does not disclose whether the stated amount refers to investable assets, retirement accounts, total net worth, or another measure.
Other details that could affect how readers interpret the outcome are missing, including the amount and timing of his contributions, the allocation within the equity funds, fees, inflation adjustment, taxes, and any employer contributions. The reported 9.5% annual return is not accompanied by a measurement method, comparison benchmark, or year-by-year results.
The retiree’s expectation of adding another million every few years is a personal forecast, not a confirmed outcome. The profile gives no account of future market performance, withdrawals, health costs, or other changes that could affect his assets. His planned Roth conversions and the timing and effect of required minimum distributions are also not detailed.
Retirement Plans and Tax Decisions
The retiree said he plans to keep his assets in equity index funds and continue investing, although he can no longer contribute to IRAs. He expects his investments to keep growing and said he believes he may add another million every few years; that remains his expectation rather than a guaranteed result.
He also said he intends to make Roth conversions each year before required minimum distributions start, aiming to reduce future tax bills. The profile does not give a timeline, amounts, or further details about how he will manage the conversions. It reports that he has a will but does not describe any broader estate plan.
No follow-up, account documentation, or independent assessment of his finances is included in the supplied report. The next developments in his personal plan—such as conversion decisions, withdrawals, and investment results—are not specified.
Key Questions
How did the Missouri retiree say he reached $1 million?
He said he regularly maximized contributions to an IRA and state deferred-compensation plan and invested the money in low-cost equity mutual funds. He reported reaching $1 million about 10 years ago.
How much does he say he has now?
He told Kiplinger he has more than $2 million. The profile does not specify the exact balance or define which assets are included.
Is the reported 9.5% return independently verified?
The source material presents the figure as the retiree’s own account of his average annual return over more than 30 years. It provides no calculation method or independent verification, and past returns do not guarantee future results.
Why is he considering Roth conversions?
He said his earlier savings were mainly in traditional IRAs and that he expects tax bills when required minimum distributions begin. He plans annual Roth conversions to reduce those taxes, but the profile does not include a tax analysis or schedule.
Does the profile provide financial advice?
No. Kiplinger describes the series as personal accounts intended to show how people built savings, not as financial advice. The retiree’s results and strategy may not apply to other people.
Source: kiplinger.com